How Do I Avoid Lifestyle Inflation?
Have you ever received a salary increase or started earning more, only to wonder where all the extra money went?
You may have upgraded your home, started eating out more often, bought a better phone, or simply become comfortable spending a little more here and there. Before long, what once felt like a generous income may barely seem like enough.
The tendency to spend more when your earnings increase is known as lifestyle inflation.
While enjoying the results of your hard work isn’t necessarily wrong, getting in the habit of spending more money can make it harder to save, prepare for emergencies, give generously, and work towards important financial goals.
Fortunately, there are some steps we can take to find a healthier balance.
Let’s take a look at:
- Understanding what lifestyle inflation is and why it happens
- Recognising the signs of lifestyle inflation in your own life
- Creating a plan for salary increases and additional income
- Setting financial goals before upgrading your lifestyle
- Practising contentment instead of constantly pursuing more
- Using biblical principles of stewardship to make wiser financial decisions
Before we can overcome lifestyle inflation, we have to know where it comes from.
Understanding what lifestyle inflation is and why it happens
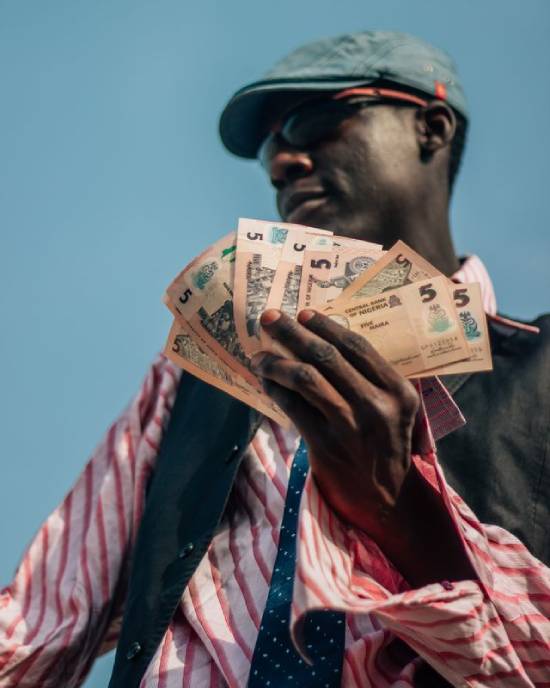
Photo by Meshack Emmanuel Kazanshyi
Lifestyle inflation happens when your spending increases as your income increases. So instead of directing a raise towards savings, investments, debt repayment, or other financial goals, you use it to pay for luxuries, or more stuff, that you couldn’t afford before.
Imagine you receive your first significant raise. You can now afford a nicer apartment, more takeaway meals, frequent rides instead of public transport, and a few extra subscriptions. Individually, these decisions might appear harmless. But together, they can use up a lot of your income.
Some lifestyle improvements may be reasonable. The problem arises when increased spending becomes an automatic reflex instead of a carefully thought-out decision.
Lifestyle inflation can happen because we naturally adjust to what we have. Things that once seemed like luxuries can slowly begin to feel like necessities. Social pressure can contribute too.
Seeing friends or colleagues upgrading their phones, cars, clothing, or holidays may tempt us to measure financial progress by what we can display rather than the financial security we are building.
So how can you tell if lifestyle inflation is already affecting you?
Recognising the signs of lifestyle inflation in your own life
One of the clearest signs of lifestyle inflation is earning more money without making meaningful progress towards your financial goals. Your income has increased, but your savings account, emergency fund, investments, or debt balance hardly reflect that growth.
Other warning signs may include:
- Your monthly expenses rise whenever your income rises.
- You regularly make impulse purchases because you can “afford” them.
- Your fixed expenses consume an increasingly large percentage of your income.
- You struggle to explain where your money went at the end of the month.
- Saving happens only when there is money left over.
- Purchases that once felt optional now seem essential.
- You depend on your next salary despite earning more than you used to.
A budget can make these patterns easier to recognise. Compare your current spending habits with those from six or twelve months ago. Which expenses increased because of genuine needs?
Which ones simply expanded because more money became available?
This exercise isn’t meant to make you feel guilty. It’s about getting clarity. Once you know where your money is going, you can decide whether your spending reflects what matters most to you.
Spotting the pattern is only half the solution. The next step is deciding what to do with your extra income.
Creating a plan for salary increases and additional income
One effective way to prevent lifestyle inflation is to decide beforehand how you will use a raise, bonus, or other increase in income. Without a financial plan, extra money can easily disappear into everyday spending.
Suppose you receive a raise. Instead of immediately going to splurge, decide how much will go towards priorities such as:
- Building your emergency fund
- Paying off debt
- Increasing your savings
- Contributing towards retirement
- Building long-term investments
- Giving
- Enjoying a reasonable lifestyle upgrade
Instead of using whatever you have left at the end of the month, you can use automatic transfers to move part of your income into savings or investments once you’re paid. This will help you prioritize what matters most and avoid wasteful spending.
Planning and being intentional is a big part of making good financial decisions.
Proverbs 21:5 reminds us, “The plans of the diligent lead surely to plenty, but those of everyone who is hasty, surely to poverty” (NKJV).
Of course, there’s nothing wrong with enjoying some of a raise, but it’s important to maintain balance. That way, you don’t have to limit the enjoyment of your money to the present—you can enjoy it in the future as well.
And that brings us to our next point…You’re most motivated to save money when you know what you’re saving for.
Setting financial goals before upgrading your lifestyle
Without defined priorities, the excitement of earning more can easily become permission to spend more. But clear financial goals give you something to work toward instead.
This might include saving enough for an emergency fund, clearing debt, pursuing further education, preparing for marriage, buying a home, investing, or building towards retirement and financial independence.
Whatever your goal is, make it specific. Instead of saying, “I need to save more money,” decide how much you want to save and by when. Then include that amount in your budget.
Then, the next time you think about taking on a new expense, ask yourself:
“Will this purchase move me closer to my financial goals or make them harder to achieve?”
This is especially important to ask when you’re dealing with regular expenses. A one-time celebration after a raise may have a limited impact, but upgrading your rent, car payments, subscriptions, or other monthly commitments can affect your finances for years.
Building wealth often looks less impressive from the outside than spending wealth. And advertisements and peer pressure make it easy to believe we can never have enough. But learning to be content can help us find joy and gratitude in what we already have.
Practising contentment instead of constantly pursuing more
Contentment helps us enjoy what we have instead of focusing on what we don’t.
This doesn’t mean we abandon ambition, financial growth, or the enjoyment of good things. It means refusing to let possessions determine whether our lives feel successful or meaningful.
It’s true that we face constant pressure to compare our lives with someone else’s. But Hebrews 13:5 encourages us to “…be content with such things as you have…” (NKJV).
Besides helping us avoid wasteful spending, contentment helps us find joy and gratitude in the little things. Instead of constantly focusing on the next upgrade, we can recognise how far we’ve already come.
To adopt a content mindset, we can start asking ourselves these questions before making an impulsive purchase:
- Do I genuinely need this?
- Am I buying it because someone else has it?
- Will I still value it several months from now?
- What financial goal could this money support instead?
Sometimes waiting 24 or 48 hours before making a non-essential purchase is enough to help us distinguish a genuine desire from a passing impulse.
When we become content, we’re able to see the bigger picture. We stop thinking of money as something we spend, but something entrusted to us to manage wisely.
Using Biblical principles of stewardship to make wiser financial decisions
Biblical stewardship encourages us to treat our money, opportunities, and resources as gifts from God that we manage with wisdom and purpose.
Jesus taught in Luke 14:28 about sitting down and counting the cost of a project before starting it. Though the immediate context of His analogy is discipleship, the illustration also highlights the practical wisdom of considering costs before making commitments.
That same habit can help with everyday financial decisions. Before increasing your lifestyle, consider what the decision will cost not only today but over time.
Build a lifestyle that supports your financial future
Lifestyle inflation can happen quietly, but it doesn’t have to determine your financial future.
When your spending habits reflect your priorities, money becomes a useful tool rather than something that constantly controls your choices.
Visit the Finance section of Hope for Africa for more practical, Bible-based insights to help you make thoughtful financial decisions.
Here are three helpful reads to explore:
- How Do I Make Wise Money Choices When I Feel Overwhelmed?
Financial decisions are especially difficult when you have competing priorities and aren’t sure what to tackle first. This article can show you how to approach money choices thoughtfully instead of letting stress or uncertainty drive your decisions. - Principles for Personal Financial Management
Good financial habits are easier to build when they are grounded in sound principles. This article can help you manage your income, spending, savings, and other financial responsibilities. - Tips for Financial Wellbeing
Financial wellbeing involves more than simply earning more money. How you manage what you have can influence your sense of stability and your ability to prepare for the future. This article offers practical ways to improve your relationship with your finances.
Avoiding lifestyle inflation is not about denying yourself every comfort. It is about learning to use your money so your income grows, and so your savings, generosity, investments, and progress towards your financial goals can grow too.
In the end, your next financial decision doesn’t have to be perfect. It just needs to be intentional.